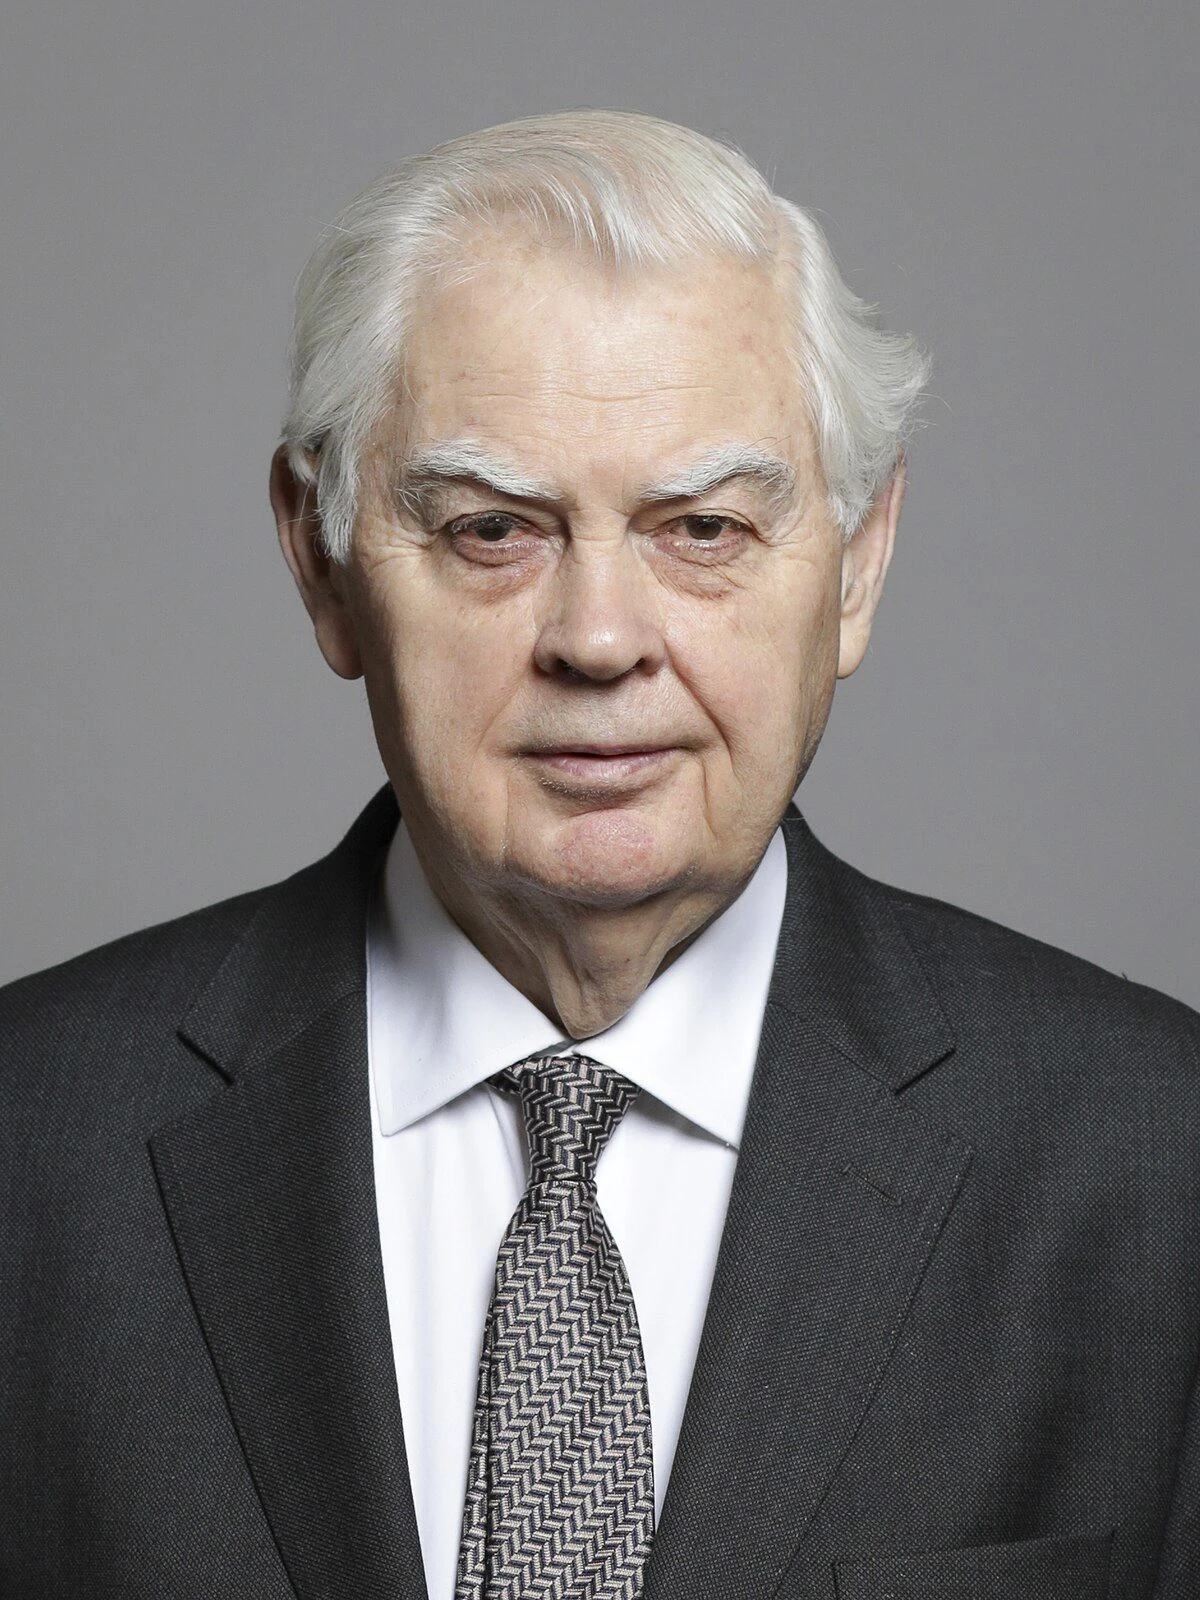
Norman Lamont’s chancellorship is inseparable from 16 September 1992, when sterling left the European Exchange Rate Mechanism (ERM). The episode, known as Black Wednesday, damaged the government’s credibility and became the defining image of his time at the Treasury. Yet Lamont’s economic record also includes the monetary framework introduced after the exit, tax and spending decisions made during recession, and negotiations over Britain’s place in European monetary union.
From Shetland to the Treasury
Norman Stewart Hughson Lamont was born in Lerwick, Shetland, on 8 May 1942. His father was the islands’ surgeon. In 1953 the family moved to Grimsby, where his father took up a position at Scartho Road Infirmary. Lamont was educated at Loretto School in Musselburgh and studied economics at Fitzwilliam College, Cambridge. At university he chaired the Cambridge University Conservative Association and became president of the Cambridge Union Society in 1964.
Before entering Parliament, Lamont worked for the investment bank N M Rothschild & Sons and became a director of Rothschild Asset Management. He stood unsuccessfully for Kingston upon Hull East in 1970, then won a by-election in 1972 to become MP for Kingston-upon-Thames. He served in government under Margaret Thatcher and John Major in departments including Energy, Industry, Defence and the Treasury.
His Treasury career began as Financial Secretary in 1986. In 1989 he became Chief Secretary, succeeding John Major. In that role he accepted Major’s decision to take sterling into the ERM, announced in October 1990. Lamont was not involved in, or informed of, the decision beforehand. When Major became prime minister the following month, Lamont succeeded him as Chancellor of the Exchequer.
Inflation, recession and Europe
Lamont took office with inflation high and the economy in recession. The government’s priority was to bring inflation down. Interest rates had reached 15 per cent in October 1988 and stood at 14 per cent when sterling joined the ERM. They were progressively reduced during 1991, but the room for further cuts was limited by conditions in Germany, where inflation rose and the Bundesbank increased its discount rate. The ERM linked the currencies of its members, constraining the government’s freedom to set interest rates for domestic conditions.
Lamont publicly defended membership as part of the anti-inflation strategy. In a Commons debate, he argued that depreciation under floating exchange rates might offer only temporary gains in output and competitiveness while leaving a lasting effect on inflation. He also supported Major’s effort to negotiate an opt-out from the proposed European single currency. At the Maastricht negotiations, Lamont sought to ensure that Britain would not have to join, that its opt-out would be legally secure, and that the country would not face binding obligations on the way to monetary union. He insisted that sterling’s ERM membership should not become a treaty obligation; the proposal was removed.
His description of “green shoots” of recovery in October 1991 was widely criticised as premature. Later assessments cited in the Wikipedia account point to the recession reaching its trough in the fourth quarter of 1991, with sustained growth resuming in the third quarter of 1992. Lamont’s optimistic phrase became a lasting shorthand for the risks of making confident public predictions during a downturn.
Black Wednesday and its consequences
On 16 September 1992, pressure on sterling made continued ERM membership untenable. The current article describes Lamont’s attempt to defend the pound through interest-rate increases, including a proposed rise to 15 per cent; the Wikipedia account supplies a broader context, recording that rates had fallen to 10.5 per cent in 1991 and that sterling’s position was increasingly difficult amid differing inflation and interest-rate conditions in Britain and Germany. By the end of Black Wednesday, the government had withdrawn sterling from the mechanism.
The exit was a political failure for a policy the government had treated as central. Lamont had assured the public only a week earlier that Britain would remain in the ERM. He was criticised for the collapse and for his apparent composure afterwards. A remark that he had been singing in the bath was turned into a story that he was pleased to have left the mechanism. In his later account, Lamont described the ERM as a tool that had broken after accomplishing what it could usefully do; his explanation acknowledged both its role in reducing inflation and the pressure created by the exchange rate needed to maintain membership.
Leaving the ERM allowed the government to set interest rates without defending a fixed exchange rate. In October 1992 Lamont set out a new monetary framework centred on an inflation target, alongside measures of money growth, attention to asset prices and the exchange rate, and more regular publication of monetary assessments. The Bank of England was asked to produce a quarterly inflation report. This framework was a precursor to the inflation-targeting system later associated with the Bank’s independence in 1997; it should not be confused with the later transfer of operational responsibility.
Budgets, departure and later politics
Lamont also faced rising public borrowing as recession reduced tax receipts, unemployment increased spending and falling inflation altered the real value of planned expenditure. His March 1993 budget announced staged tax increases intended to reassure markets about borrowing while avoiding damage to recovery. The budget was sharply criticised at the time. Later commentary cited in the Wikipedia account gave it a more favourable assessment, crediting the fiscal measures and the post-ERM framework with helping to put public finances and monetary policy on a new footing.
Lamont left the Treasury on 27 May 1993, after Major offered him a demotion to the Environment department, which he declined. In a Commons resignation speech he said the government gave “the impression of being in office but not in power”. His departure followed a period of intense scrutiny and came after the Conservatives’ heavy defeat in the Newbury by-election. The split between the policy’s failure and the subsequent recovery has shaped later assessments of his chancellorship: leaving the ERM was a public humiliation, but the shift to a floating exchange rate made a different monetary policy possible.
After leaving office, Lamont became a prominent critic of the Major government and argued for a more sceptical approach to European integration. His 1995 book, Sovereign Britain, set out a case for withdrawal from the European Union. He lost his Kingston-upon-Thames seat after constituency changes ahead of the 1997 election, then lost the contest for Harrogate and Knaresborough. In 1998 he entered the House of Lords as Baron Lamont of Lerwick. His later activities included chairing the Economic Research Council from 2008 and offering advice to Greece’s finance minister Yanis Varoufakis during the 2015 debt negotiations.
Why Norman Lamont deserves a place in British Legacy
Lamont’s place in British political history rests first on a decision taken under extraordinary market pressure: Britain’s departure from the ERM. That exit exposed the cost of trying to hold sterling to a fixed exchange rate while domestic and German economic conditions diverged. It damaged the government’s authority, and Lamont, as Chancellor, became its most visible representative. The consequence was not simply a humiliating day in the markets. The end of the peg opened the way to a different approach to interest rates and monetary policy, including the inflation-targeting framework he announced in 1992. That framework preceded, but was distinct from, the Bank of England’s later independence.
His wider record also matters. Lamont helped negotiate Britain’s opt-out from the proposed single currency at Maastricht, and his budgets addressed the fiscal pressures left by recession and falling inflation. These were contested choices, not a smooth or universally praised programme. Setting them alongside Black Wednesday gives a fuller account of how economic policy is made: governments must weigh price stability, employment, exchange rates, public borrowing and political credibility, often when those aims conflict. For British Legacy, Lamont’s story is valuable not as a simple tale of failure or vindication, but as a case study in the long consequences of crisis decisions and the policy changes that follow them.
Sources
Norman Lamont — revision 1379199304 · Norman Lamont
Adapted in part from Norman Lamont by Wikipedia contributors, under CC BY-SA 4.0. Text has been edited and combined with the existing article; this adapted text is shared under the same licence. Contributor history.